Expectancy First: Win Rate vs Payoff for Traders, R Normalization
Traders: learn an expectancy first method. Use breakeven 1/(1+R), R normalize trades, run rolling windows, and size positions to limit ruin.
Expectancy First: Win Rate vs Payoff for Traders, R Normalization
Win rate tells you how often you’re right. Payoff ratio tells you how much you make when you are, versus how much you lose when you’re wrong. Neither number alone proves a strategy is profitable. What matters is expectancy, the combination of both, and the fastest sanity check is the breakeven win rate formula: 1 / (1 + payoff ratio). Run that math before you trust any strategy’s stats, including your own.
TL;DR:
- A strategy’s profitability depends on expectancy, which combines win rate and payoff ratio and is confirmed by the breakeven win rate formula.
- A 2:1 payoff ratio requires just over 33.3% win rate to break even, making higher payoff ratios easier to maintain with lower win rates.
- Trend-following, mean reversion, and scalping each have distinct typical win rate and payoff profiles, influencing their psychological and risk management traits.
- Reliable evaluation of win rate and payoff ratio demands at least 30 to 100 normalized trades, with rolling windows and outlier stress-testing for accurate insight.
- Traders often overestimate their edge by trusting raw numbers, so conducting thorough trade audits and simulations helps verify true expectancy before risking larger amounts.
Table of Contents
- Win Rate vs Payoff: The Math That Actually Determines Expectancy
- Breakeven Win Rate: Quick Reference and Worked Examples
- How Trading Style Shapes Your Win Rate and Payoff Profile
- How to Measure Win Rate and Payoff Without Fooling Yourself
- Turning Expectancy Into Position Size Without Blowing Up Your Account
- What a Trade Audit Reveals About Your Real Win Rate and Payoff
- Why Traders Chase the Wrong Number
- Verify Your Numbers Before You Trust Them
- Sources
- FAQ
Win Rate vs Payoff: The Math That Actually Determines Expectancy
Win rate is simply wins divided by total trades. Payoff ratio compares your average win to your average loss: if your average winner nets $300 and your average loser costs $150, your payoff ratio is 2:1.
Neither figure means much in isolation. The number that actually settles the argument is expectancy, and there are two ways to calculate it:
- In dollars: Expectancy = (Win% × Average Win) − (Loss% × Average Loss)
- In R-multiples: E® = (Win% × R) − (1 − Win%), where R is your payoff ratio expressed as a multiple of risk
That second formula is worth memorizing because it strips out position size entirely. A trader risking $500 per trade and one risking $50 per trade can compare notes directly once everything is expressed in R. This R-multiple framing is the backbone of how academic work on win rate and payoff shape capital growth, and it’s also standard vocabulary in most win rate calculation methods used across performance tracking.
Here’s the part that trips people up: two completely different win rate and payoff combinations can produce identical expectancy. Same expectancy, wildly different trading experience.
Breakeven Win Rate: Quick Reference and Worked Examples
Before you evaluate any strategy, run this test: divide 1 by (1 plus your payoff ratio). That’s the minimum win rate you need just to avoid losing money, before commissions and slippage even enter the picture. This is the same breakeven logic laid out in payoff ratio definitions and formulas, where a 2:1 payoff needs just over 33.3% wins to break even.
Quick reference for common payoff ratios:
- 1:1 payoff → 50% breakeven win rate
- 2:1 payoff → 33.3% breakeven win rate
- 3:1 payoff → 25% breakeven win rate
- 5:1 payoff → 16.7% breakeven win rate
Two worked examples make this concrete. A day trader running a 1:1 payoff needs to win more than half their trades just to tread water, meaning a win rate below the breakeven threshold leads to losses no matter how disciplined the execution looks. A swing trader running 3:1 needs only 26 winners out of 100 to turn a real profit, assuming zero friction costs. The margin for error shrinks fast once real costs enter the equation.
Pro Tip: If your backtested win rate is sitting within 5 percentage points of your breakeven number, you don’t have an edge. You have noise that will flip against you the moment costs or volatility shift.
How Trading Style Shapes Your Win Rate and Payoff Profile
Your strategy type largely dictates where you’ll naturally land on the win rate vs risk reward spectrum, and fighting that tendency usually backfires.
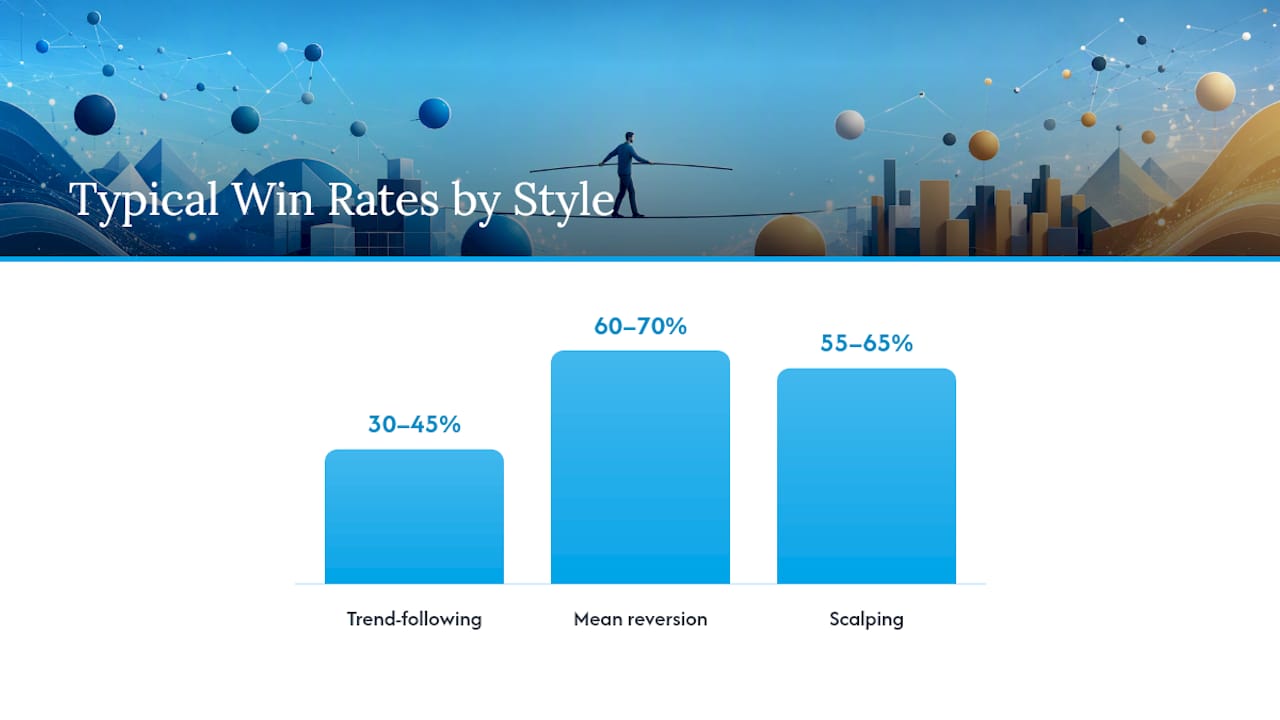
- Trend-following: typically 30% to 45% win rate with 2x to 4x payoff. Most trades lose small; the occasional trend runner covers everything and then some.
- Mean reversion: typically 60% to 70% win rate with 0.6x to 1x payoff. High hit rate, thin edge per trade, vulnerable to the occasional trend day that blows through every reversal signal.
- Scalping: typically 55% to 65% win rate with payoff near 1x. Frequency and consistency replace big individual wins.
These profiles produce very different equity curves. Trend-followers sit through long stretches of small losses punctuated by sharp equity jumps, which is psychologically brutal even when the math is sound. Mean-reversion traders see smoother, more frequent gains, but they’re exposed to sudden, sharp drawdowns when the market trends against them. This tradeoff is well documented in analysis of how win rate and payoff pull against each other across systematic strategies.
Pro Tip: If losing streaks wreck your discipline, gravitate toward higher win-rate strategies even if the payoff is thinner. If you can stomach ten losers in a row without touching your stop-loss rules, higher R strategies tend to be more forgiving of the occasional bad month.
How to Measure Win Rate and Payoff Without Fooling Yourself
Raw win rate and payoff numbers lie more often than traders expect, mostly because of small samples and inconsistent position sizing.
- Collect at least 30 to 100 trades per setup before drawing conclusions. Anything less and your confidence interval is wide enough to make a 55% win rate statistically indistinguishable from 40%, a caution echoed in guidance on win rate and payoff ratio reliability.
- Normalize every trade to R before averaging. If your position size varies from trade to trade, a raw dollar-based payoff ratio is meaningless. Convert wins and losses to multiples of initial risk first.
- Stress-test for outliers. Remove your top one or two winning trades and recalculate the payoff ratio. If it collapses, your edge depends on a couple of lucky trades rather than a repeatable process.
- Run rolling 50-trade windows instead of a single lifetime average. A strategy that looked great over 200 trades might have earned that entire edge in one 30-trade hot streak.
Turning Expectancy Into Position Size Without Blowing Up Your Account
Once you have a real expectancy number, the next question is how much to risk per trade, and this is where most traders get greedy.
The Kelly criterion gives a mathematically “optimal” bet size based on your edge, but full Kelly sizing is aggressive enough to produce brutal drawdowns even with a genuine edge. That’s why most practitioners size at one-quarter to one-half Kelly, trading some theoretical growth for a smoother ride and a much lower chance of ruin, an approach outlined in discussions of win rate versus risk reward tradeoffs.
- Subtract commissions and slippage from your expectancy calculation before sizing, not after.
- Make sure your realized win rate clears breakeven by a real margin, not by a rounding error.
- Treat risk-of-ruin as a separate question from expectancy. A positive-expectancy strategy sized too aggressively can still go to zero on a bad streak.
Pro Tip: Run a Monte Carlo simulation on your actual trade history before committing to a position size. Seeing 1,000 randomized equity paths built from your own numbers is far more convincing than any theoretical Kelly calculation.
What a Trade Audit Reveals About Your Real Win Rate and Payoff
Most traders calculate win rate and payoff once, from a spreadsheet, and never revisit the number. That’s how a strategy with a genuinely fragile edge keeps getting traded for months.
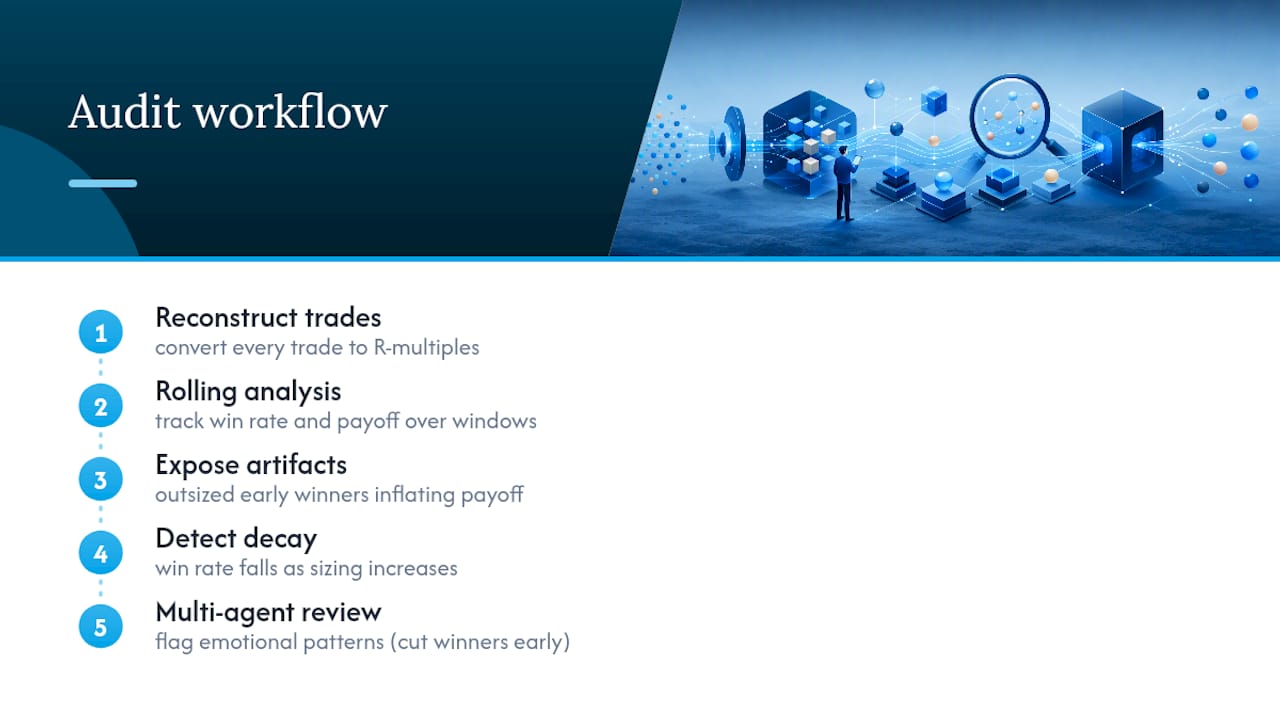
A proper audit reconstructs every trade into R-multiples first, then tracks win rate and payoff over rolling windows rather than a single lifetime average, similar to reviewing a Performance Ratios tab instead of a static summary. That rolling view often exposes something a lifetime average hides entirely: a payoff ratio propped up by two outsized winners early in the sample, or a win rate that decayed the moment position sizing crept up. Multi-agent trade review can also flag emotional patterns, like cutting winners early on some setups but not others, that quietly distort the payoff side of the ledger without ever showing up as a “mistake” in a basic P&L review.
Why Traders Chase the Wrong Number
The obsession with win rate is mostly about ego. A high win rate feels like being right, and being right feels good, so traders will happily trade a thinner payoff just to keep that feeling. I’d argue the more useful discipline is treating expectancy as the only number that matters and treating both win rate and payoff as inputs you’re allowed to be wrong about individually, as long as the combination clears breakeven with room to spare. Small samples lie convincingly, so stay humble about any edge under 100 trades.
— DigitalPunk
Verify Your Numbers Before You Trust Them
Most traders never actually check whether their win rate and payoff ratio hold up under real scrutiny, they just trust whatever their broker statement or spreadsheet spits out. Some platforms perform multi-agent audits that reconstruct trade history into R-multiples, track win rate and payoff on rolling windows instead of one static lifetime number, and run Risk of Ruin simulations to estimate survival odds, not just theoretical edge.
You can start with the free Read-Only Inspection to see how the platform reconstructs your trades before committing to anything. For traders ready to upload real data and get full multi-agent analysis, the Pro plan runs $12.50 per month or $150 per year. If you want a broader look at what the trading journal and analytics solutions cover beyond win rate and payoff, that overview walks through the rest of the toolkit. Check your own numbers against a real breakeven calculation before you size up another trade.
Sources
- What is Payoff Ratio? Definition, Formula & Examples (JournalPlus)
- Win Rate vs Payoff Ratio - Why One Number Tells You Nothing (Trends & Breakouts)
FAQ
Is a 30% Win Rate Good?
It depends entirely on your payoff ratio.
What Is a Payoff Ratio?
Payoff ratio is your average winning trade divided by your average losing trade, expressed as a ratio like 2:1 or 3:1. A 2:1 payoff ratio means your typical winner is twice the size of your typical loser.
Is a 40% Win Rate Good?
Plenty of profitable trend and swing strategies run in the 30% to 45% win rate band precisely because their payoff ratios compensate for it.
What Does Win Rate Mean?
Win rate is the percentage of trades that close as winners, calculated as wins divided by total trades. On its own it says nothing about profitability. A strategy needs its win rate checked against its payoff ratio through the breakeven formula before anyone can call it an edge.
How Do I Know if My Win Rate Numbers Are Reliable?
Reliability depends on sample size and consistent position sizing. Aim for at least 30 to 100 trades normalized to R-multiples, and check whether a rolling Winrate Over Time view tells a different story than your lifetime average.
Recommended
Stop reviewing from memory
Run compliance scoring, tag ranking, and Kill List rules on every trade — not once a month when the account feels off.